
By Advantage Gold | May 2026
When most people think about silver, they think about jewelry. Coins. A cheaper alternative to gold for investors who can’t afford the yellow metal.
That mental model is dangerously incomplete — and investors who hold it may be missing one of the most compelling commodity stories of the decade.
Silver is not just a precious metal. It is an industrial metal. And the industries consuming it are not slowing down. They are accelerating.
Gold is primarily a monetary metal. Its demand comes overwhelmingly from investors, central banks, and jewelry buyers, and central bank demand remains a major support for gold across broader commodity markets. Industrial use accounts for roughly 10-15% of annual gold demand.
Silver is different. Industrial demand accounts for approximately 59% of total annual silver consumption — and that share has been growing steadily as the global economy electrifies and digitizes, making industrial usage a key driver of the silver market.
This dual nature — part monetary metal, part critical industrial input — gives silver a demand profile unlike any other asset. Silver’s role now extends into future technologies, while investment demand and investment flows can amplify silver value through higher volatility across economic cycles and market cycles. That mix means silver investment is shaped not only by physical demand, but also by macroeconomic factors.
Both of those tailwinds are blowing simultaneously right now, making silver one of the most compelling commodity stories of the decade.
The list of modern technologies that depend on silver is long, and growing:
Solar panels are perhaps the most significant current driver. Each solar panel contains approximately 20 grams of silver, used in the conductive paste that makes the cells work efficiently. Global solar installations have been growing exponentially — and projections for the next decade suggest the pace will accelerate significantly as governments worldwide push toward renewable energy targets and broader solar power deployment. The Silver Institute has estimated that solar photovoltaic technology alone could consume 200+ million ounces of silver annually within this decade.
Electric vehicles require silver in multiple components — circuit boards, battery management systems, charging infrastructure, and the sensors and cameras that power advanced driver assistance systems. As EV adoption scales globally, silver demand from the automotive sector is projected to rise dramatically, with the metal becoming increasingly essential to more electrified transport systems.
5G infrastructure relies heavily on silver for its superior electrical conductivity. Every 5G base station, every connected device in the emerging Internet of Things ecosystem, requires silver. As 5G rollout continues globally and the number of connected devices multiplies, this demand stream compounds.
Semiconductors use silver in bonding wire and contact points throughout the chip manufacturing process. As the world’s appetite for chips continues to grow — driven by AI, data centers, smartphones, and consumer electronics — silver consumption in semiconductor manufacturing grows with it.
Artificial intelligence data centers are a newer but rapidly growing demand driver. The server infrastructure powering AI requires sophisticated electronics — and silver is embedded throughout, underscoring how future technologies are expanding its industrial footprint.
While demand grows, supply has structural constraints that few investors appreciate.
Silver is rarely mined primarily as a target metal. Approximately 70-75% of annual silver supply comes as a byproduct of mining for other metals — primarily lead, zinc, copper, and gold. This means silver supply cannot simply be ramped up in response to higher prices the way a pure silver mine could scale production, which is central to the market’s supply-demand dynamics.
When copper demand rises, more copper gets mined and some silver comes with it. But the relationship between silver prices and silver supply is far weaker than for most commodities, because the mining decisions aren’t primarily driven by silver economics.
Primary silver mines — those focused specifically on silver production — represent a small fraction of total supply and have seen limited new development in recent years due to underinvestment in the sector broadly. That matters for silver price forecasts because constrained output can amplify the effect of rising industrial use.
The result is a metal where demand is growing structurally and supply is constrained structurally. That is a setup that commodity analysts watch closely.
Before the industrial demand story existed, silver was money. For most of human history, silver coins were the primary medium of everyday commerce — gold was for large transactions and reserves, silver was what people used to buy bread.
The United States was officially on a bimetallic standard — both gold and silver — until the late 19th century. Silver remained in US coins until 1964. The monetary heritage of silver is long and deep.
That heritage is re-emerging in policy discussions. Multiple US states have now passed legislation recognizing silver as legal tender alongside gold. The Trump administration has reportedly explored a silver price floor. The same legislative momentum building around gold is beginning to build around silver too, even as central bank buying continues to shape the broader precious-metals backdrop.
Silver sits at a unique intersection: it has the monetary characteristics of gold and the industrial demand profile of copper. In a world where both monetary uncertainty and technological acceleration are simultaneously at historic highs, that dual nature is a powerful asset, especially when trade tensions push investors toward hard assets alongside steady fabrication demand.
One metric precious metals investors watch closely is the gold-to-silver ratio — how many ounces of silver it takes to buy one ounce of gold.
Historically, the ratio has averaged roughly 15:1 to 20:1, reflecting the approximate natural abundance of each metal in the earth’s crust. In recent decades, the ratio has traded much higher — often above 70:1, and at times above 100:1 during periods of market stress.
At a ratio above 80:1, silver is historically cheap relative to gold. When the ratio compresses — as it has done in previous precious metals bull markets — silver tends to outperform gold significantly on a percentage basis, a move often amplified when retail investors increase participation across ETFs, physical holdings, and futures.
This doesn’t mean silver will always close the gap quickly. But it means that investors who hold silver as a complement to gold are holding an asset with both a strong fundamental demand story and a historical tendency to outperform during precious metals bull markets, which is why silver price forecasts often weigh investment flows and market structure alongside industrial demand.
Silver deserves a place in the conversation about precious metals investing — not as a substitute for gold, but as a complement.
Gold is the cornerstone of a sound money strategy: the monetary reserve, the safe haven, the multi-thousand-year store of value. Silver brings an additional dimension: industrial demand that is structurally tied to the technologies defining the 21st century economy.
Together, they offer diversification within the precious metals space — one primarily monetary, one straddling monetary and industrial — in an environment where both safe haven demand and technology demand are simultaneously elevated.
At Advantage Gold, we help investors understand how both gold and silver can work together as part of a comprehensive wealth protection strategy. Physical silver, like physical gold, can be held in a self-directed IRA — offering the same tax advantages as traditional retirement accounts while providing real, tangible asset exposure, and silver investment also reflects how the silver market responds to both portfolio allocation and real-world usage.
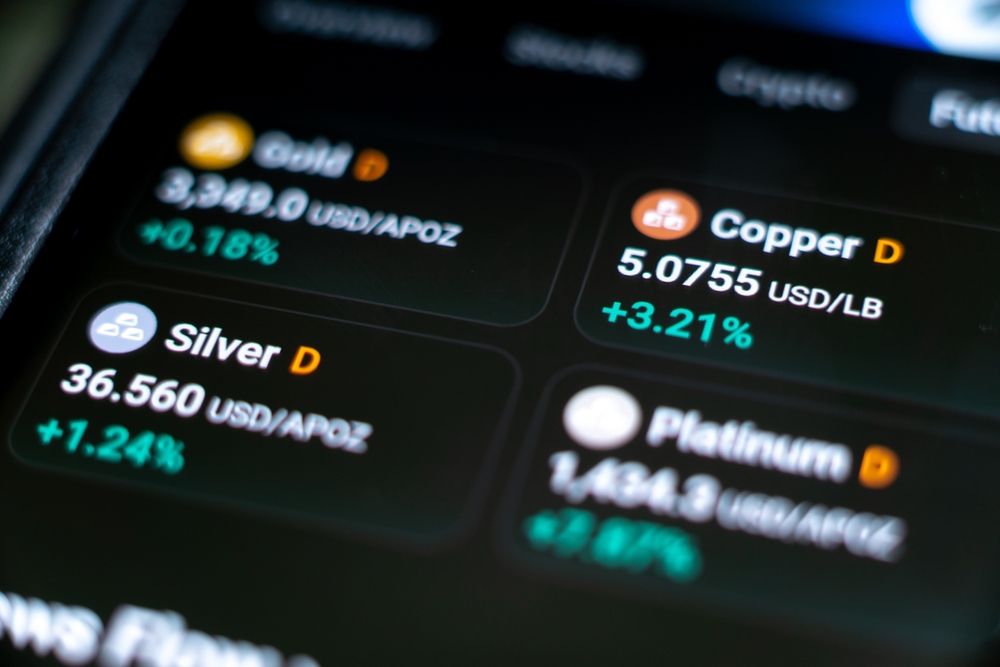
The technology revolution needs silver. The monetary system’s uncertainty needs silver. The supply constraints create scarcity. The historical ratio suggests relative value. In recent decades, the ratio has traded much higher, and by 2026 silver prices had reached roughly US$94 per ounce globally, a level not seen in decades. At a ratio above 80:1, many investors view silver as historically inexpensive relative to gold. Silver price forecasts often use that ratio alongside broader market context. That can strengthen investment demand when the gap begins to close, especially as investment flows return quickly during momentum-driven moves.
The case for silver has rarely been more compelling. Retail investors often re-enter the market aggressively when silver begins outperforming gold in bull phases.
Advantage Gold specializes in helping Americans protect their wealth through physical gold and silver. To learn more about adding silver to your portfolio or IRA, visitadvantagegold.com.